In the dynamic landscape of North American banking, real-time notifications have become a cornerstone of modern security strategies. These notifications serve as critical tools for banks, allowing…
Read More
 Latinia

Updated on September 4, 2026
Regulatory compliance has become a strategic pillar for financial institutions, especially amid increasing regulatory demands and growing international pressure to prevent money laundering. In this context, AML (Anti-Money Laundering) policies are no longer just a legal obligation—they are now essential tools for protecting a bank’s reputation, ensuring operational stability, and strengthening customer trust.
This article reviews how AML works in banking, which regulatory frameworks are currently in force, which controls form part of an effective program, and how technology can help financial institutions execute these processes with greater speed and traceability.
AML (Anti-Money Laundering) is the set of policies, processes, and technologies a financial institution uses to prevent illicit funds from entering the financial system. It relies on linked controls: customer identification and verification, assessment of customer risk, continuous transaction monitoring, and reporting suspicious activity to the relevant authority.
The framework varies by region: in the European Union, the new AML/CFT package combines the AML Regulation, AMLD6, and the new AMLA authority; in the United States, the Bank Secrecy Act and the Anti-Money Laundering Act remain central. In every case, the underlying requirement is the same: detect risks in time and be able to demonstrate what happened.
AML plays a critical role in the banking sector because of the central position financial institutions occupy in the global flow of capital. Banks process millions of transactions daily, and any weakness in their control systems can enable the legitimization of illicit funds, leading to serious economic and reputational consequences. A widely cited estimate from the United Nations Office on Drugs and Crime (UNODC) places the scale of money laundering at between 2% and 5% of global GDP.
Institutions that fail to comply with AML regulations face steep penalties, a loss of customer trust, and significant legal risks. According to Fenergo’s latest global analysis, penalties related to AML, KYC, sanctions, and customer due diligence reached $3.8 billion in 2025.
Beyond legal requirements, AML has become a strategic priority. An effective program not only ensures regulatory compliance but also helps safeguard the integrity of the financial system, deters organized crime, and reinforces the bank’s credibility with customers, investors, and regulators.
An AML program combines preventive and detective controls that begin before a customer relationship is established and continue throughout the customer lifecycle. The objective is to understand who is operating, assess their level of risk, identify unusual behavior, and report suspicious activity when required.
To understand what these controls are designed to detect, it is useful to distinguish the three classic stages of money laundering:
To counter these stages, banks apply controls throughout the customer relationship: customer identification and verification (Know Your Customer or KYC), risk assessment, continuous transaction monitoring, and reporting suspicious activity to the relevant financial intelligence unit.
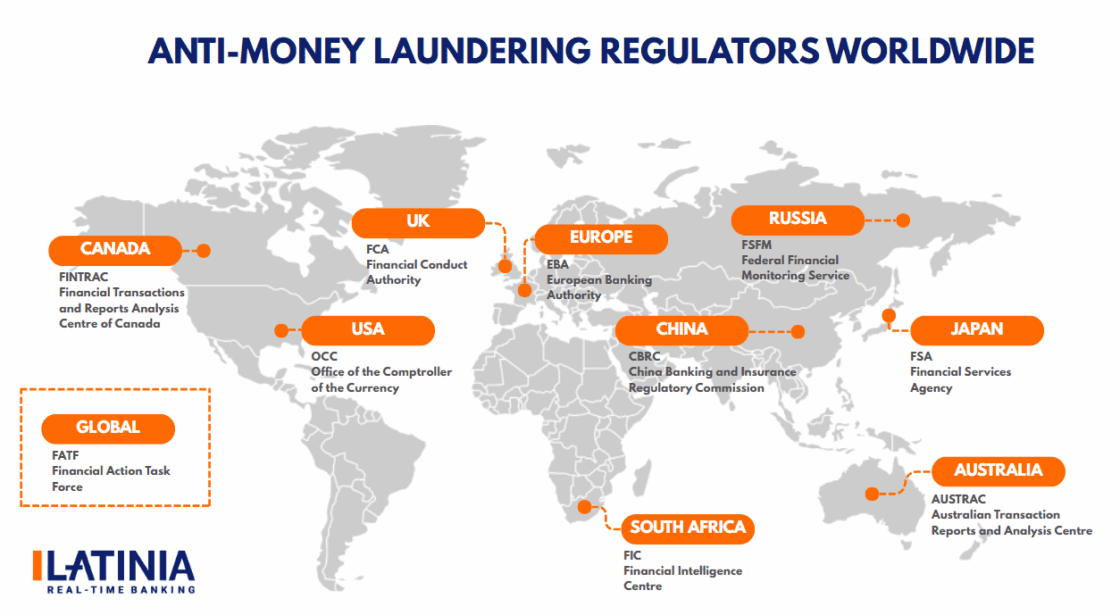
Compliance with AML regulations in the banking sector takes place within a global landscape that is constantly evolving. While rules differ across regions, they all share the same core objective: to stop the flow of illicit funds, protect the integrity of the financial system, and prevent crimes such as corruption, fraud, and terrorist financing.
Europe’s anti-money laundering framework is in transition toward a more harmonized system. The AML/CFT package adopted by the European Union in 2024 includes Regulation (EU) 2024/1624 (AMLR), which will generally apply directly from July 10, 2027, and Directive (EU) 2024/1640 (AMLD6), which strengthens and harmonizes national prevention, supervision, and cooperation mechanisms.
The new framework also includes the Authority for Anti-Money Laundering and Countering the Financing of Terrorism (AMLA), legally established in 2024 and based in Frankfurt. The authority began most of its operations in 2025 and continues to build out its capabilities during 2026. In 2027, it is expected to select up to 40 high-risk entities for direct supervision beginning in 2028.
The new AMLD6 should not be confused with Directive (EU) 2018/1673, also commonly referred to as the Sixth Anti-Money Laundering Directive (6AMLD), which remains relevant in the criminal-law context and sets rules on money-laundering offenses, sanctions, and the liability of legal persons.
In the United States, AML regulations are primarily shaped by the Bank Secrecy Act (BSA), enacted in 1970, and reinforced by the Anti-Money Laundering Act of 2020 (AMLA). This reform modernized the BSA/AML framework, strengthened beneficial ownership transparency, and extended regulatory attention to emerging risks and sectors. The Financial Crimes Enforcement Network (FinCEN) administers the BSA and continues to update the framework: in April 2026, it proposed a further reform of AML/CFT program requirements aimed at moving toward more effective, risk-based models.
According to the latest figures published by FinCEN, approximately 4.8 million Suspicious Activity Reports (SARs) were filed in fiscal year 2025, compared with 4.6 million in 2023.
In Canada, AML enforcement is led by the Financial Transactions and Reports Analysis Centre of Canada (FINTRAC). The agency monitors compliance across sectors such as banking, insurance, casinos, real estate, and activities involving virtual currencies, among others, and receives several types of reports, including suspicious transaction reports.
Latin America has strengthened its regulatory frameworks to align with the international standards of the Financial Action Task Force (FATF). In the region, the Financial Action Task Force of Latin America (GAFILAT) includes, among other countries, Mexico, Colombia, Brazil, Chile, and Peru, and promotes implementation of international standards against money laundering and terrorist financing.
Each country also develops its own legislation and has competent authorities and financial intelligence units responsible for receiving, analyzing, and, where appropriate, disseminating information on suspicious transactions.
Complying with AML regulations requires more than basic controls—it demands a proactive and structured approach that enables financial institutions to identify risks, act quickly, and adapt to evolving regulatory frameworks.
Below are the key strategies that help strengthen compliance in the banking sector.
Risk assessment should not be a one-time task. Banks must conduct continuous reviews that cover customer behavior, the nature of the products and services offered, and relationships with third parties such as ultimate beneficial owners.
A strong identity verification process is the first step in preventing financial crimes. Banks must collect and validate data such as name, address, date of birth, and beneficial ownership, using both traditional methods and advanced digital solutions. This process forms an essential part of customer due diligence before and throughout the business relationship, according to the applicable risk level and regulatory requirements.
Ongoing transaction monitoring helps detect unusual activity or suspicious behavior patterns. This includes monitoring transactions that exceed certain thresholds and analyzing repeated low-value transfers that may signal smurfing techniques.
Additional data points—such as digital signals, IP analysis, or information associated with devices and channels—can provide an extra layer of context for validating customers and detecting risks when their use is compatible with applicable regulation. This information can complement traditional sources and improve the quality of customer due diligence.
Banks should design AML policies that, in addition to meeting regulatory requirements, adapt to each customer’s risk profile. This means adjusting controls according to factors such as economic activity, source of funds, or country of residence, while maintaining a customer-centric approach.
The adoption of advanced technologies—such as real-time transactional data monitoring platforms, rules engines and machine-learning models, or automated identity verification—can optimize specific AML processes, reduce manual tasks, and enable faster action when risks arise.
Continuous staff training is essential to maintaining the effectiveness of an AML program. All employees should understand their role in risk detection and remain up to date on emerging threats and regulatory changes.
Maintaining open communication channels with competent authorities and cooperating in the detection and investigation of suspicious activities strengthens a bank’s compliance posture and reinforces its commitment to financial integrity.
Technology tools perform different functions within an AML architecture. Some specialize in customer identification and verification, screening, or transaction monitoring; others make it possible to turn signals generated by those systems into immediate decisions and actions. This real-time response layer is particularly relevant when a financial institution needs to act quickly and preserve a traceable record of what happened.
Some of the most impactful solutions for enhancing AML programs include:
In this context, Latinia does not replace a specialized AML or KYC platform, but it brings a unique advantage to meeting security and compliance requirements. Its real-time decision software can integrate with a financial institution’s transaction, fraud, risk, or compliance systems to receive events and signals, apply rules, and activate the communications or actions defined by the bank.
It’s not just about sending alerts—Latinia offers a decision engine capable of:
In this way, Latinia can complement the bank’s security and compliance architecture, helping ensure that signals generated by specialized systems translate into timely, traceable decisions and communications.
Get in touch with Latinia for a consultation, or visit our website for more information.
AML (Anti-Money Laundering) refers to the prevention of money laundering: the set of policies, processes, and technologies a financial institution applies to prevent illicit funds from being integrated into the financial system, and to detect them when an attempt is made.
It relies on linked controls: customer identification and verification before transactions begin, assessment of customer risk, continuous transaction monitoring for suspicious patterns, and reporting questionable activity to the relevant financial intelligence unit.
In Europe, the framework is evolving toward the European Union’s new AML/CFT package, which includes the AML Regulation (AMLR), Directive (EU) 2024/1640 (AMLD6), and the new European AMLA authority. In the United States, the Bank Secrecy Act of 1970 was later reinforced by the Anti-Money Laundering Act. Each region adds its own regulators and reporting deadlines, meaning an international banking group must operate across several frameworks at once.
KYC (Know Your Customer) is part of AML, not a synonym for it: it identifies and verifies who the customer is and what level of risk they represent. AML also includes continuous transaction monitoring, detection of suspicious patterns, and the obligation to report them.
It makes it possible to assess each transaction as it happens, rather than in a batch process the following day, and trigger an alert or block before the money leaves. It also preserves a record of what was detected, when it was detected, and what action was taken—precisely the type of evidence regulators require institutions to be able to demonstrate.
Contact