Last updated: October 19, 2026
Hyper-personalization in banking applies these same principles to financial services: using each customer’s behavior, needs and context to decide which services, recommendations or communications will be most useful to them. It isn’t just about making individual offers, but about linking every decision to the customer’s situation and the moment it happens.
In recent years, banking has undergone a significant shift in customer experience (CX). Digital has reshaped customer expectations, pushing banks to keep innovating to meet changing needs. Today’s customers want convenience, speed and personalization, which is driving banks to move from traditional service models to more customer-centric approaches. Technology hasn’t just streamlined banking operations; it has also opened up new ways to boost customer engagement and satisfaction.
What is hyper-personalization and how is it different from personalization?
According to IBM, hyper-personalization draws on granular data such as browsing behavior, location and contextual factors (time of day, for example) to tailor experiences to each customer. This closer attention to context goes beyond simply using a customer’s name or purchase history.
It helps to distinguish between three related concepts:
- Segmentation: groups customers who share characteristics or needs in order to shape a strategy.
- Personalization: tailors products, content or messages based on known attributes or preferences.
- Hyper-personalization: also uses individual data and context to decide which offer or interaction makes sense in each situation.
These practices aren’t mutually exclusive: customer segmentation in banking helps identify groups and plan strategies, while hyper-personalization helps decide, customer by customer, what to communicate.
Hyper-personalization in banking goes beyond standard practices. It can rely on advanced data analytics, artificial intelligence (AI) and machine learning (ML) to deliver individualized experiences. Real-time data and predictive analytics help banks understand customers’ preferences, behaviors and financial needs, so they can tailor products, services and communications more precisely.
Why hyper-personalization matters in retail banking
Deloitte identifies hyper-personalization (experiences tailored to each customer or household) as one of the shifts reshaping retail banking, alongside digitalization and the growing role of financial advice. This evolution means moving from a one-size-fits-all offering to relationships built around each customer’s circumstances.
Banks need to evolve from product-centric to customer-centric models, a transition that is key to staying competitive in a fast-changing market. This shift isn’t only about offering digital services; it’s about using customer data to create more meaningful, personalized banking experiences. Banks that make this transformation can expect greater customer loyalty, higher satisfaction and, ultimately, more revenue.
Traditional banking has been defined by a one-size-fits-all approach, with standardized products and services. Digital technologies, however, have enabled banks to move toward hyper-personalized services. This shift is driven by customer demand for services that fit their unique financial situations and preferences. Banks are now focusing on understanding individual customer journeys and using data analytics to deliver solutions that match each customer’s specific needs.
Real-world applications and use cases in banking
Hyper-personalization has practical applications that are transforming the banking sector. Here are five key use cases where it is making a significant impact:
- Personalized product recommendations: Banks use customer data to recommend financial products suited to individual customer profiles. The approach is similar to the personalized shopping experience offered by leading e-commerce platforms.
- Dynamic pricing and offers: Based on a customer’s transaction history, credit score and other financial behaviors, banks can offer dynamic pricing on loans, credit cards and other financial products, along with personalized offers and rewards.
- Personalized financial advice: With hyper-personalization, banks can provide tailored financial advice, including investment suggestions, savings plans and budgeting tips based on the customer’s financial history and goals.
- Predictive customer service: By analyzing past interactions and preferences, banks can anticipate customer needs and address them proactively, leading to a more responsive service experience.
- Fraud detection and prevention: Hyper-personalization also plays a key role in improving security. By understanding customers’ typical behavior patterns, banks can quickly spot and respond to unusual and potentially fraudulent activity.
Technologies that enable hyper-personalization
The role of artificial intelligence and machine learning
Artificial intelligence (AI) and machine learning (ML) can be important tools for hyper-personalization in banking. They allow banks to process large volumes of data and turn it into actionable insights into customer preferences and behaviors. AI algorithms can analyze transaction patterns, spending habits and even social media activity to tailor banking services to individual needs. And machine learning models improve over time, continuously refining personalization as they take in more data.
Using big data for tailored banking services
Big data plays a fundamental role in enabling hyper-personalized banking services. By analyzing large datasets, banks can gain a comprehensive understanding of their customer base, including demographics, transaction history, online behavior and even lifestyle choices. With these insights, banks can create highly personalized customer experiences. For example, big data can help identify life events such as buying a home or planning for retirement, so banks can offer relevant financial products at the right time.
Real-time analytics and channel management for personalized communications
Delivering hyper-personalized experiences depends heavily on real-time analytics and effective channel management. Both are essential for interpreting customer data and delivering personalized communications across touchpoints.
Real-time analytics allow banks to make instant decisions based on current customer data. This could include changes in spending behavior, current browsing activity or significant life events. By analyzing this data as it happens, banks can deliver immediate, relevant offers, advice and solutions that fit each customer’s current context and needs.
Effective channel management ensures these personalized interactions happen on the customer’s preferred platforms, whether through an app notification, email, SMS or a personalized web experience. Seamless multichannel integration is key to engaging customers where they are most active and receptive.
Technologies that coordinate these interactions need to be able to:
- Interpret relevant customer data and events.
- Apply rules and decision criteria suited to each customer’s context.
- Coordinate communications across available channels, respecting customer preferences.
- Measure results to improve future decisions.
These capabilities need to integrate with the bank’s existing systems and contribute to a more relevant, consistent experience.
How Latinia helps banks build hyper-personalization strategies
Latinia is a software platform for real-time banking communications that connects a bank’s transactional systems with its communication channels. Within a hyper-personalization strategy, it analyzes events in context and applies rules to decide what to notify, to whom and when, and also manages delivery. It relies on the data and criteria defined by each bank.
- RTD Universal: analyzes events and applies the bank’s rules to trigger transactional, operational, security or compliance communications.
- RTD NBA/O (Next Best Action / Next Best Offer): identifies the right moments for service, loyalty and offer actions based on the customer’s context.
- RTD Subscription: lets each customer set up the alerts they want to receive, with their own conditions and channels, within the bank’s catalog.
- Critical Notifications Gateway (SDP): manages the delivery, prioritization and traceability of sensitive notifications across multiple channels and providers.
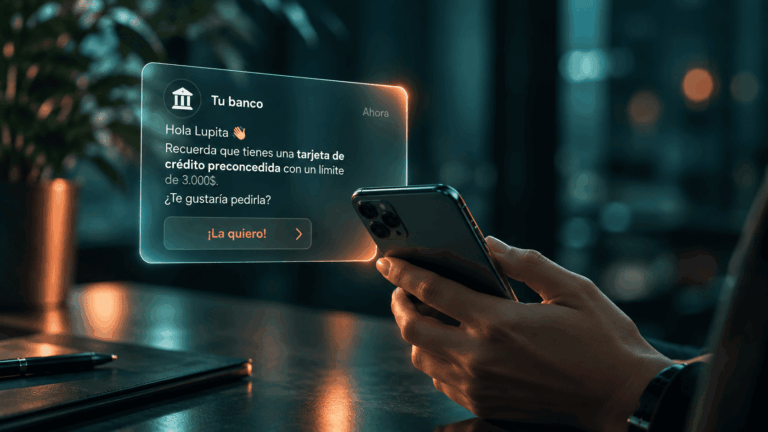
For example, after a banking transaction, the bank can check whether there is relevant information to share, evaluate the customer’s preferences and decide whether to send a notification. Latinia’s contribution focuses on decisioning and communication; customer financial knowledge and offer design remain in the bank’s hands.
This ties directly into the relevance and timing of banking communications: it isn’t just about personalizing a message, but about determining whether it actually adds value for the customer at that moment.
EXPERT TIP
Before automating new communications, identify which banking events reflect a real customer need. Hyper-personalization isn’t about seizing every opportunity to send a message; it’s about deciding when an interaction adds value and when it’s better not to communicate at all.
Hyper-personalization strategies for banks
Customer-centric product design
In hyper-personalization, a customer-centric approach to product design is essential. It means creating banking products and services that not only meet customers’ current needs but also anticipate future ones. Deloitte’s insights highlight how important it is for banks to understand customers at an individual level. That deep understanding makes it possible to design financial products that resonate with specific customer segments.
For example, a bank could offer a credit card with features tailored to frequent travelers, or a savings account with unique benefits for students. These tailored products meet customer needs more effectively and improve the overall customer experience, building a sense of value and belonging.
Driving customer engagement and loyalty
Hyper-personalization also plays a critical role in driving customer engagement and loyalty. Banks that use data to understand customer behavior and preferences can create more meaningful interactions. This can take the form of personalized communication strategies, where banks reach customers with relevant information at the right time, through the right channels, with the help of tools like Latinia.
Capgemini’s World Retail Banking Report 2025 notes that personalized communications, real-time assistance and tailored rewards can strengthen banking customer engagement, and links relevant rewards to long-term loyalty.
For example, sending a personalized money management tip via a mobile app notification, or offering a personalized investment plan by email. This kind of relevance increases engagement and builds trust and loyalty, because customers feel understood and valued.
Challenges and ethical considerations
Balancing personalization and privacy
While hyper-personalization offers many benefits, it also raises challenges, particularly around privacy. Customers are increasingly aware of their data privacy rights and concerned about how their personal information is used. Banks need to strike a careful balance between delivering personalized services and respecting customer privacy. That means being transparent about how data is collected and used, obtaining explicit consent and giving customers options to control their data.
The European Data Protection Board points out that profiling involves the automated analysis of personal data to evaluate aspects such as preferences, interests or economic situation. That’s why banks need to pay close attention to the responsible use of this data and to the safeguards that apply to automated decision-making.
Data security and regulatory compliance
Data security and regulatory compliance are other major challenges in the age of hyper-personalization. As banks collect and analyze more customer data, the risk of data breaches grows. Banks must put strong cybersecurity measures in place to protect customer information. They also have to comply with a complex web of privacy and data protection regulations, such as the GDPR in Europe and various state laws in the US. Navigating these regulatory landscapes requires a proactive approach to compliance and a commitment to ethical data practices.
The revenue benefits of advancing personalization maturity
The path to hyper-personalization isn’t only about customer satisfaction; it has a demonstrable impact on a bank’s revenue. The personalization maturity curve, shown in the chart below, illustrates a clear path of revenue growth as banks progress through the different stages of personalization maturity.
From simple message delivery to more sophisticated predictive personalization, each step up the personalization ladder correlates with a tangible increase in revenue. This is reflected in the substantial sales figures reported by industry leaders who attribute a significant share of their revenue to hyper-personalized recommendations.
For example, as banks move from inserting generic fields into communications to rules-based segmentation, they see higher customer engagement, which translates into more sales. This progression gains momentum as banks adopt behavioral recommendations and omnichannel optimization, culminating in the sophisticated approach of predictive personalization. At this stage, banks aren’t just reacting to customer behavior, but anticipating needs, leading to proactive service that customers are willing to pay for.
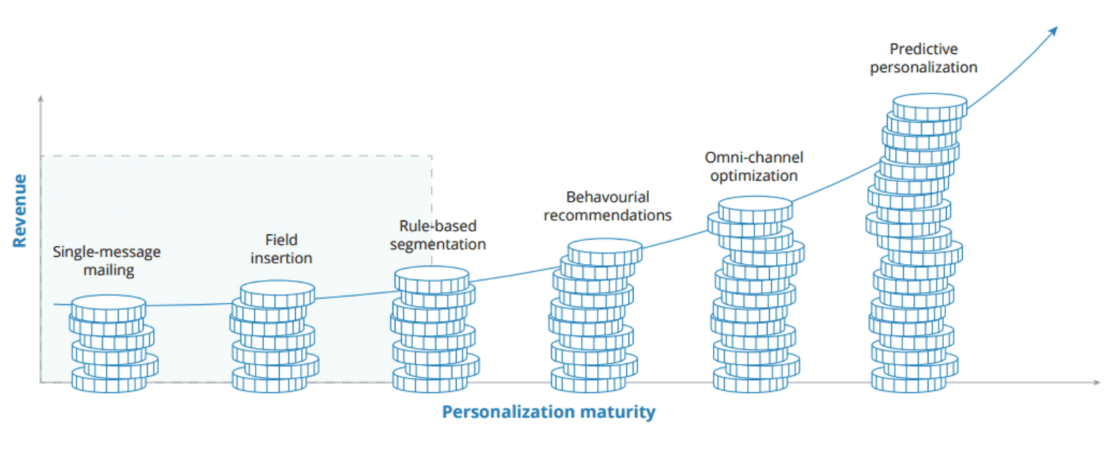
Source: The future of retail banking: The hyper-personalization imperative – Deloitte
The case for hyper-personalization is further strengthened by success stories from non-banking companies like Amazon and Netflix, which have used hyper-personalization to drive 35% and 60% of their sales, respectively. Similarly, Starbucks has seen its incremental revenue triple through the strategic use of hyper-personalized offers.
Conclusion
Hyper-personalization can improve the banking experience when data is turned into decisions that are useful, relevant and respectful of customer preferences. The value isn’t in multiplying offers or notifications, but in identifying what each person needs and when it makes sense to act.
To put it into practice, banks need to combine customer knowledge, business criteria and technology capable of acting on events and coordinating communications. Latinia provides specialized software for real-time banking decisioning and communication that can support this last piece, integrated with the bank’s own systems and data.
If you’d like to explore how to apply these capabilities to your bank’s communications, talk to the Latinia team.
Frequently asked questions about hyper-personalization
What’s the difference between personalization and hyper-personalization?
Personalization tailors messages, content or products to a customer’s known attributes. Hyper-personalization also takes their behavior, needs and context into account to decide which interaction is relevant in a specific situation.
What are some examples of hyper-personalization in banking?
Recommending savings options based on a customer’s needs, tailoring a notification to a recent transaction, or holding back a communication that isn’t timely are all examples of how it applies in banking.
Does hyper-personalization require artificial intelligence?
Not necessarily. AI can help recognize patterns or prioritize recommendations, but business rules, events and customer preferences also make individualized decisions possible.
Does hyper-personalization have to happen in real time?
Not always. Real-time events are useful when a transaction or signal requires an immediate response, but hyper-personalization can also be applied in scheduled or deferred processes.