
Last updated: November 3, 2026
The banking industry is at a critical juncture, shaped by the rapid rise of digital technologies and changing customer demands. A global study by Temenos and Celent, published in September 2026 and based on 2,515 banking consumers, found that 51% want their bank to better anticipate their needs when they use the app or call, while 58% want more financial guidance. The message for banking professionals is clear: success depends on digital innovation, strong security and a customer-centric approach.
Recognizing and responding to these preferences is essential for marketing and business development leaders in banking. Customers want more than convenience: they want assurance that they’re secure and a deeper connection with their financial services.
KEY TAKEAWAYS
- Banking customers value security, trust, ease of use, helpful support and transparent pricing.
- Banking customer preferences depend on factors such as life stage, channel and type of service, not just generation.
- Speed alone isn’t enough: customers expect clear, relevant communications delivered at the right moment.
- Research from 2026 points to growing demand for digital control and personalization, trends worth watching heading into 2027.
Digital banking: a must-have for consumers
Changing customer expectations have turned digital banking from a convenient option into an essential service. Digital transformation in banking is about more than keeping up with tech trends; it’s about meeting a non-negotiable consumer demand. This preference highlights the need for banks to prioritize their digital offering.
Essential features of digital platforms
Digital banking platforms are at the heart of today’s banking interactions and serve as the main channel for a wide range of financial activities. Here’s what customers look for in their digital banking experience:
- Easy access: Being able to bank anytime, anywhere is fundamental. Consumers expect a seamless experience across devices, whether through a mobile app or a web browser.
- Full range of services: From checking balances to applying for loans, customers prefer a digital one-stop shop for all their banking needs, minimizing the need to visit a physical branch.
- User-friendly interface: An intuitive design that works for users of every level is crucial. A simple, engaging user experience can significantly boost customer satisfaction and loyalty.
Security and fraud protection: the backbone of trust
The convenience of digital banking comes with a critical concern: security. Protecting customers’ personal and financial information is paramount. The same Temenos and Celent study found that 39% of consumers surveyed are dissatisfied with the security and fraud protection they get from their bank. Effective measures include:
- Encryption technology: Ensuring all transmitted data is securely encrypted to prevent unauthorized access.
- Multi-factor authentication (MFA): An added layer of security that requires multiple forms of verification before granting access to the user’s account.
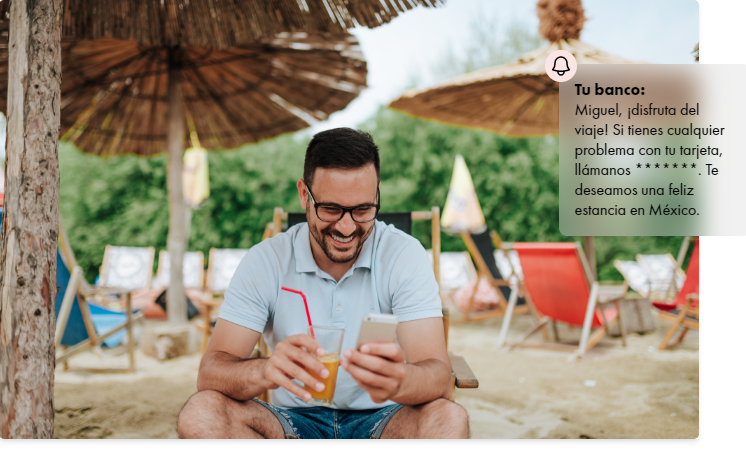
- Real-time alerts: Notifying customers of account activity can help quickly detect and prevent fraudulent transactions.
Trust depends as much on preventing fraud as on informing customers when a suspicious transaction is detected. Real-time critical alerts make it possible to flag risk situations and enable a fast response.
Experian’s 2026 report also highlights the importance of offering secure access processes without adding unnecessary friction.
Customer service goes digital
Digital banking isn’t limited to transactions; it’s also about maintaining and strengthening the customer relationship through digital channels. Quality customer service in the digital age means:
- 24/7 support: Round-the-clock support, powered by AI chatbots and live support teams.
- Personalized financial advice: Using data analytics to offer tailored advice and product recommendations based on customer behavior and preferences.
- Proactive problem-solving: Anticipating and addressing potential issues before they become a problem for the customer.
Beyond having multiple channels, users value knowing what’s happening with their transactions and receiving alerts that help them act. Relevant, timely communication can confirm a transaction, warn of an incident or support a decision, without requiring the customer to constantly check the app. That’s very different from simply sending more messages.
Meeting expectations through banking communications
Meeting these expectations also means deciding what information the customer needs, when and through which channel. Banks can combine transactional alerts, service communications and personalized messages, while respecting each user’s preferences and the priority of critical notifications.
Latinia is real-time banking communications software that connects banking events with decisions about what to communicate, to whom and when, based on the rules defined by each bank.
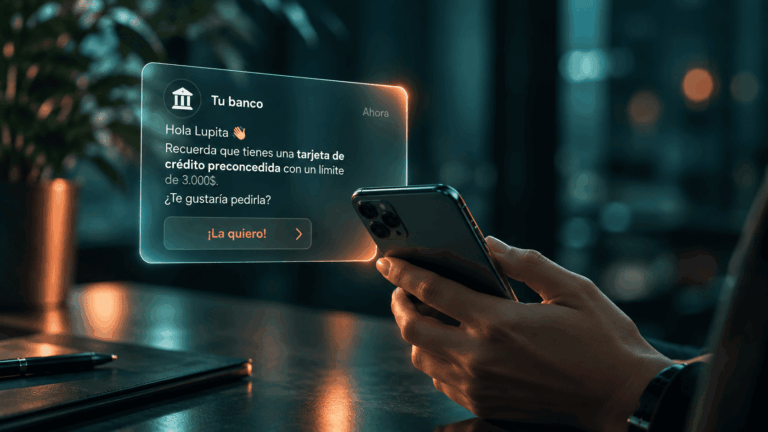
Latinia allows banks to interpret transactional events and apply decision rules in real time to trigger relevant communications. With the RTD Universal Engine, banks can respond with alerts related to transactions or banking situations. The RTD Next Best Action (NBA/O) Engine, meanwhile, identifies timely service actions or offers based on the customer’s context and the bank’s criteria. This helps address specific needs without turning every interaction into a sales pitch.
Finally, the RTD Subscription Engine lets customers set certain notification preferences, such as channel, transaction type or amount, within the bank’s rules. This level of personalization gives customers more control, without affecting the critical alerts that must be sent regardless of subscription.
Why competitive interest rates matter
The appeal of favorable interest rates on savings accounts, personal loans and other financial products can strongly influence where consumers choose to keep their money or who they borrow from. This section looks at consumer preferences around interest rates and how they vary across generations.
Consumer preferences on savings and loan rates
Interest rates are more than numbers: they directly reflect the value consumers get from their banks. In The Ascent’s 2024 US survey, stated preferences included:
- Savings accounts: Nearly half of respondents (49%) in 2024 considered savings account interest rates the most important factor in a competitive financial product. This shows how much weight consumers place on growing their savings efficiently.
- Personal loans: Personal loan rates also carried significant weight, with 15% of respondents prioritizing competitive rates in this category. This reflects consumers’ desire for affordable borrowing options.
Generational differences shape banking preferences: Gen Z focuses on digital banking and personal loans, Millennials and Gen X value digital convenience and competitive rates, and Baby Boomers prioritize high savings rates and certificates of deposit for financial security. In the next section, we take a closer look at these different priorities.
Understanding what customers value in a bank also means considering transparent terms, the fees charged and how easy it is to compare products.
Generational trends in banking preferences
From Gen Z to Baby Boomers, each group has its own priorities, shaped by technological advances, economic conditions and life stages. This section explores the nuances of these generational differences and the changing importance of ATM access, branch locations and account fees.
Alkami’s 2026 study, based on 1,500 US digital banking users, shows differences in control, financial education, support and security; these preferences also depend on each person’s situation and market.
Banking priorities across generations
These preferences can be grouped by generation, although each customer has their own needs and habits:
- Gen Z: Digital natives through and through, Gen Z prioritizes mobile banking features, digital payment options and innovative financial products. They care less about traditional banking services such as physical branches or ATM access, and place more value on speed, convenience and tech integration.
- Millennials: Bridging digital and traditional banking, Millennials appreciate online banking capabilities but also value in-person consultations for complex financial matters. They are especially fee-sensitive and prefer banks that offer no-fee accounts and transparent pricing.
- Gen X: With many at the peak of their careers or managing solid financial portfolios, Gen X values a mix of digital efficiency and personalized financial advice. They are more likely to combine online and in-branch banking, balancing convenience with the need for deeper financial planning and consultations.
- Baby Boomers: Having watched banking evolve over decades, Baby Boomers show a stronger affinity for traditional banking channels, including branch access and face-to-face customer service. While open to digital banking for routine transactions, they often prefer physical branches for major financial decisions and value accessible ATM networks.
The changing role of ATMs, branches and fees
The weight of in-person channels, cash access and fees also varies with each customer’s habits:
- ATM access: Once a cornerstone of banking convenience, ATM access is becoming less important for younger generations, who increasingly rely on digital payments and mobile wallets. It remains important, however, for older generations who value being able to withdraw cash without fees.
- Branches: The role of physical branches is changing. While less important for younger customers who prefer digital interactions, branches still play a crucial role for those seeking personal advice, complex financial services or who prefer to bank in person.
- Account fees: Across all generations, tolerance for high account fees is shrinking, with a clear preference for transparent, fair pricing. This is especially pronounced among Millennials and Gen Z, who actively look for banking services that offer the best value with no hidden costs.
For banks, distinguishing between profiles can help fine-tune the customer relationship, but customer segmentation in banking doesn’t replace taking individual data and preferences into account when communicating with each person.
Tailored banking solutions for generational preferences
Banks face the challenge of serving this broad range of preferences, which calls for a nuanced approach to their service offering. Understanding generational trends is essential to developing tailored banking solutions that meet each generation’s unique needs. This means adapting digital platforms and rethinking the role of traditional banking channels and fee structures to align with today’s expectations.
The banking sector’s ability to respond to these generational shifts will define its success in an increasingly competitive landscape. By adopting a customer-centric model that values personalization, convenience and transparency, banks can build lasting relationships across all age groups, laying the groundwork for future growth and innovation.
The advantages of online banking
Online banking has transformed the financial landscape, giving consumers unprecedented convenience and flexibility in managing their money. This shift has brought countless advantages that traditional banking channels struggle to match.
Lower fees and cost savings
One of the most tangible benefits of online banking is lower fees for consumers. Without the overhead of maintaining physical branches, online banks can pass these savings on to customers through lower fees and higher interest rates on savings accounts. This cost efficiency is a key driver of online banking’s popularity, as it directly benefits consumers’ wallets.
- No monthly maintenance fees: Many online banks offer checking and savings accounts with no monthly maintenance fees, in sharp contrast to traditional banks, where these fees are common.
- Higher interest rates on savings: Savings rates offered by online banks are often significantly higher than those of traditional banks, making them an attractive option for consumers looking to maximize their savings growth.
Innovative account management features
Online banking platforms offer innovative features that help consumers manage their finances more effectively and efficiently. These features provide convenience, control and insight into their financial health, all accessible from a computer or mobile device.
- Real-time alerts: Online banking lets customers set up real-time alerts for transactions, low balances and other important account activity, so they stay informed and can react quickly to any issue.
- Budgeting and financial planning tools: Many online banks offer built-in tools that help customers budget, track spending and set financial goals, giving them a full picture of their financial situation.
- Easy account opening and management: Opening and managing accounts online is simple, with most processes completed in just a few clicks. This ease of access encourages financial engagement and simplifies tasks such as transferring funds, paying bills and depositing checks via mobile deposit.
- Customizable security features: Online banks often offer advanced security options, such as temporarily locking cards, setting spending limits and customizing alert preferences, giving customers peace of mind and control over their accounts.
How technology is improving online banking
Behind these online banking advantages is advanced technology that enables banks to deliver secure, efficient and user-friendly services.
Latinia’s solutions, for example, help banks improve the relevance and timing of their communications in real time and deliver personalized banking experiences based on transaction context and customer preferences. This way, banks can trigger alerts about banking transactions and let customers set their preferences for receiving certain notifications.
The complete banking experience
Offering a single standout feature is no longer enough for banks to attract and retain customers. Today’s consumers want a complete banking experience that combines competitive rates and low fees with seamless security and unmatched convenience.
This holistic view helps explain why users don’t judge a bank on price alone. Banking customer satisfaction also depends on how problems are solved, how clear the information is and how consistent the experience is across channels.
As social values evolve, social responsibility is also playing a bigger role in banking decisions, reflecting a shift toward ethical consumerism in finance.
In practice, the balance goes beyond the product: customers value receiving understandable information, being able to choose channels and getting answers when an issue arises. That’s why customer-centric banking starts by listening to these expectations and bringing them into everyday interactions.
A balanced mix of essentials
To meet today’s consumer demands, banks need to balance competitive interest rates, minimize fees, ensure strong security and offer convenience through digital access and user-friendly services. Excelling in these areas is key to increasing customer satisfaction and standing out in a competitive market.

The role of social responsibility
Beyond financial considerations, social responsibility can influence consumers’ banking choices. Some customers align their banking with their values and prefer institutions that demonstrate environmental responsibility, social equity and community involvement. This preference reflects a demand for transparency and ethical business practices, extending to how banks invest and operate.
How banking customer expectations could evolve in 2027
Heading into 2027, some customer expectations are gaining ground. Studies published in 2025 and 2026 point to a combination of security, frictionless digital services, guidance and more relevant communications.
According to Accenture, digitalization can lead to more transactional, less personal relationships. Meanwhile, Alkami’s 2026 study found that 44% of its US sample wanted their bank to better anticipate their financial needs and goals.
- More control: the ability to adjust communication preferences, channels and optional alerts without missing critical information.
- More value in every interaction: alerts tied to real transactions, pending tasks or situations that need attention.
- More trust and clarity: explaining risks, terms and decisions in an understandable way, while keeping support channels available when needed.
For a bank, the question isn’t simply whether to send more messages or add more technology, but whether each interaction solves a specific customer need. To learn more about anticipating needs and triggering the right response, see our article on anticipating customer needs.
EXPERT TIP
Before prioritizing new features, sort expectations into two groups: those the bank must always meet (security, clarity and access) and those that depend on context (the channel, timing and content of each alert). For communications, measure not only how many messages were sent, but whether each one was useful, arrived on time and respected the customer’s preferences.
Conclusion
As banking continues to evolve, it’s clear that meeting and exceeding customer expectations is key to success. Analysis of consumer preferences highlights the demand for a complete banking experience that combines competitive rates, minimal fees, stronger security and digital convenience, along with a growing emphasis on social responsibility. Banks face the challenge of adapting to these multifaceted demands in a dynamic environment to stay competitive and relevant.
Here, Latinia helps banks respond with relevant, timely communications based on each customer’s events, context and preferences.
For banks looking to strengthen their customer relationships, real-time communication and decisioning technologies can complement their digital systems and customer experience strategies. Talk to a Latinia expert to explore how to adapt these use cases to your bank’s needs and rules.
Frequently asked questions about what banking customers want
What do customers value most in a bank?
They usually value a combination of security and trust, clear pricing, ease of use, effective support and services that fit their needs. The relative weight of each factor varies by person, market and moment.
What do customers expect from digital banking?
Simple, reliable access to their accounts, fast transactions, understandable information, data protection and support when a task can’t be solved through self-service.
What factors influence banking customer preferences?
Age and life stage play a role, but so do digital habits, financial situation, trust in the bank, costs, the complexity of each transaction and past experiences with support channels.
Why do branches still matter as online banking grows?
Because some customers prefer personal service for complex decisions, incidents or tasks that need guidance. What matters is offering continuity between digital and in-person channels.
How can a bank respond to demand for personalized communications?
It can combine transaction data with business rules and communication preferences to decide which alert is useful, when to send it and through which channel, without replacing critical communications that must be delivered.
Which needs could become more important for banking customers in 2027?
Recent studies suggest paying special attention to control over communications, simple digital processes, fraud prevention and genuinely useful interactions.